Money · PRACTICAL FIELD NOTE
The first number to check when cash is unexpectedly tight
A candid, practical field note for small-business owners about the first number to check when cash is unexpectedly tight, with a clear next step.
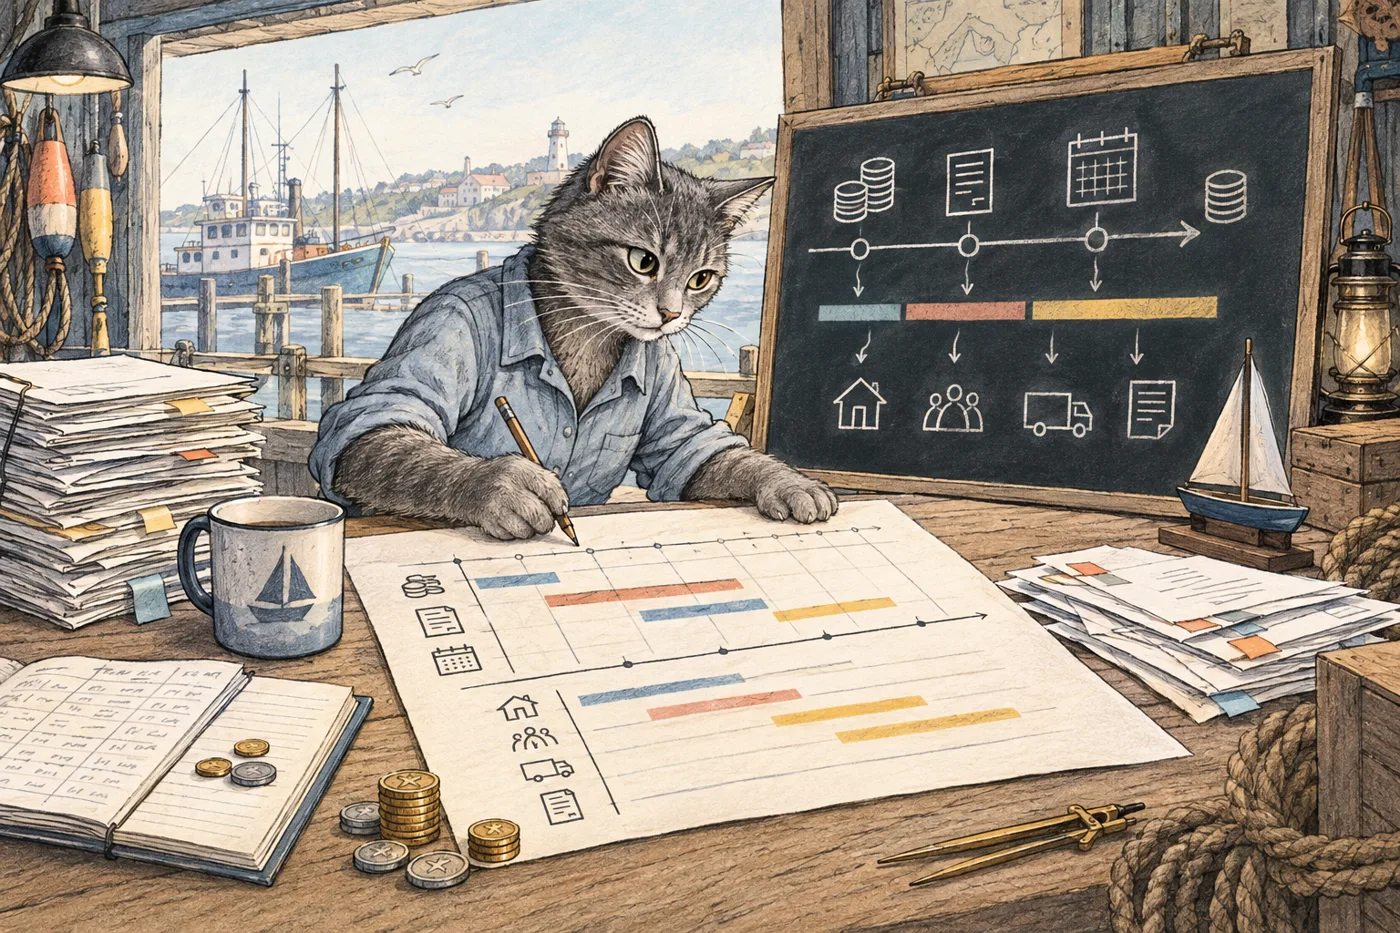
When cash feels unexpectedly tight, the bank balance can look like the obvious place to start. But a balance is only a snapshot. It may not tell you which bills are about to land, which customer payments are still pending, or how much of that cash is already spoken for. That gap matters. If you cut a useful expense or rush into a discount to bring in sales, you may solve the wrong problem. The pressure could be about timing, not a business that needs a permanent change. A calmer first check is possible, even if your records are simple. This field note will help you look ahead at incoming cash and committed outflows, spot the dates that create a squeeze, and choose a sensible next step before making a bigger decision.
What to know
Consider a hypothetical design studio with $4,000 in its account, $2,800 in rent and payroll due Friday, and a $2,000 client payment expected next week. These figures show that paying the listed Friday bills would leave $1,200 before other transactions; they do not establish a shortfall. The later payment may matter if additional commitments fall due first, but those must be included before drawing that conclusion. List available cash, expected receipts and committed bills beside their dates, then check what the figures actually show. Treat uncertain receipts cautiously: an invoice is not cash already received. A dated one-page view makes the sequence clearer before you choose a response. These invented figures are illustrative, not a forecast or benchmark.
Put it into practice
Build a dated view
A useful first pass is to set out when cash is available, when money may arrive, and when committed payments are due. Record the balance you can use today, then list expected receipts and outflows beside their dates. Include obligations such as payroll, rent, tax, suppliers and debt payments, as well as irregular bills you know are coming. Keep uncertain income visibly separate from cash already received.
Choose a horizon that fits the immediate decision. The next seven or 14 days can be a convenient starting window, not a rule: look farther ahead if a major bill or expected payment falls beyond it. If your records are incomplete, start with what you can confirm and mark estimates clearly. For each date, update the running balance using the transactions you expect. The first point where cash may fall below what you need to operate is a useful squeeze date to investigate, not a verdict on the business.
The map is a planning view, not a guarantee. A customer may pay early or late, and a bill may change. Its purpose is to make the assumptions visible so you can check the most consequential ones. If a critical payment is due immediately, confirming the amount and deadline or contacting the relevant counterparty may need to happen alongside the mapping, not afterward.
Separate cash from hoped-for cash
An invoice or verbal promise is not money in the account. For each expected receipt, note who owes it, the amount, the expected date and how certain that timing is. Where a date is unconfirmed, use a cautious estimate or show a range. That keeps a payment that might arrive from quietly carrying the weight of a bill that definitely falls due.
Then compare the map with recent transactions. Did a receipt arrive later than expected, several bills cluster together, or an expense exceed the estimate? A single timing gap may call for a different response than a shortfall that remains even when expected receipts are counted. Check several payment cycles and remember irregular expenses before treating one difficult week as a diagnosis. If the pattern persists, review revenue, recurring costs and payment terms together.
Match the response to the constraint
For a timing gap, contact the customer before the due date to confirm status and ask whether a realistic payment date or partial payment is possible. If you may need to move a supplier payment, speak early and agree what is feasible rather than assume late payment is acceptable. Review discretionary spending that is not yet committed, while distinguishing it from obligations already due.
If the figures still show a gap after expected receipts, delaying one bill may only move the pressure. Consider pricing, workload, recurring expenses and the terms on which you accept work. Before making a lasting cut, weigh what that expense enables; removing it could also affect service or future revenue. A reversible pause or small test may provide a safer basis for a larger decision. Record what you expect each action to change, update the map as transactions clear, and see whether the squeeze date moves or the same gap returns. If you cannot meet an important payment, seek appropriate professional or lender advice before making commitments you may not be able to keep.