Money · PRACTICAL FIELD NOTE
Profit looks great. Can you make payroll on Friday?
A candid, practical field note for small-business owners about profit looks great. can you make payroll on friday, with a clear next step.
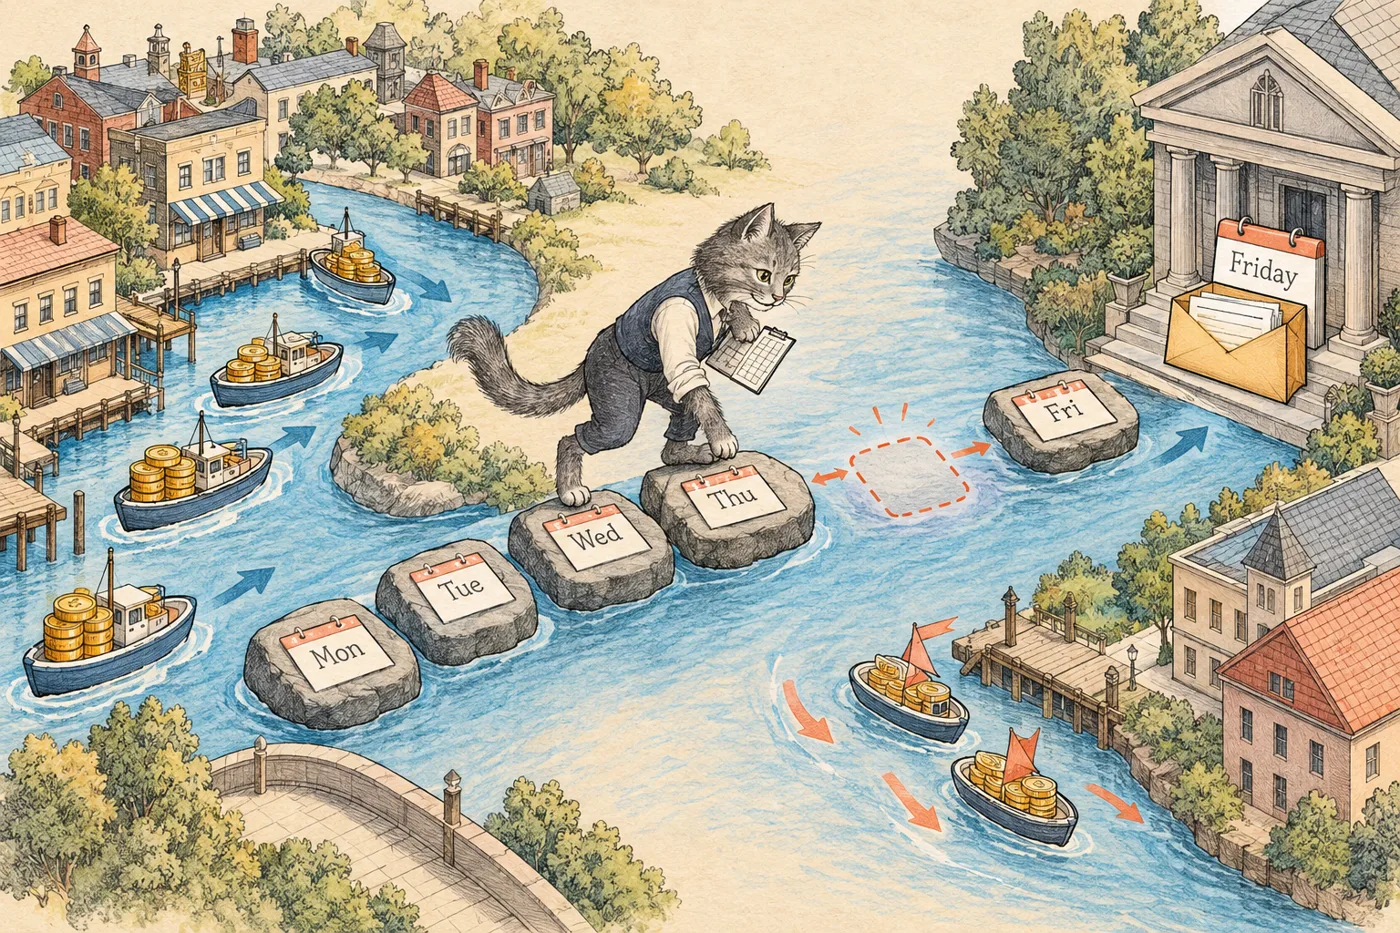
Your profit report says the month went well. Then Friday arrives, payroll is due, and a customer’s payment is still somewhere between “approved” and your bank account. The business may be profitable on paper and still feel short of cash at exactly the wrong moment. That tension is not just an accounting puzzle. If you spot a timing gap early, you may have more choices than if you discover it on payday: follow up on an invoice, delay a discretionary purchase, or talk with a supplier. None is automatic or painless, but timing can change what is possible. A useful monthly cash-flow check is less about predicting the future perfectly than seeing what is due, what is expected, and when the two might miss each other. This field note will show you how to map that timing, notice a pinch point while there is room to act, and choose one practical next step without confusing profit with cash in hand.
What to know
Consider a fictional shop with $7,000 in its bank account on Wednesday. Payroll of $5,000 is due Friday, rent of $2,000 is due Monday, and a customer’s $6,000 invoice is expected Wednesday. If that payment arrives on time, the month may look comfortable; if it arrives late, the account reaches zero before the money comes in. These figures are illustrative, not a forecast or a claim about typical businesses.
The useful decision is not whether the invoice is “probably fine.” It is what you can do before Friday if it slips. Check the payment date with the customer, identify any nonessential purchase you can postpone, and confirm when the supplier needs payment. Put each expected receipt and committed payment on a calendar by date. That simple timing view can expose a cash pinch that a profit figure alone may not make obvious, while leaving you time to consider your options.
Put it into practice
Start with a short window
Choose a manageable first pass—perhaps 15 minutes—and write down the cash you can use today. List receipts you reasonably expect and payments due over the next two weeks, with dates. Include payroll, rent, taxes, loan payments, supplier bills, and automatic charges. Treat 14 days as a starting point, not a rule: extend the view if a larger commitment falls later. Check invoices and bills rather than relying on memory where you can.
Map dates, not totals
Use a calendar or simple spreadsheet, one row per date. Begin with today’s usable balance; add receipts when you expect them to clear and subtract payments on their due dates. Carry each ending balance into the next day. In a fictional studio, a client payment expected on the 18th may follow payroll due on the 15th: monthly totals can obscure that sequence. Mark any projected low point for closer review, while remembering that estimates can shift.
Separate firm dates from hopeful ones
Label receipts confirmed, expected, or uncertain. Keep an invoice without payment confirmation visible, but do not silently treat it as cash in hand. For an important receipt, test a later arrival date—perhaps a week later if that is plausible. If the projected balance then affects a commitment, verify the payment date and ask whether anything is needed to process it. A reassuring reply is less useful than a specific date or confirmation.
Choose an action that fits the gap
Compare possible responses by timing, cost, and consequences. You might follow up on an overdue invoice, postpone a discretionary purchase, or ask a supplier whether another payment date is acceptable. Confirm terms before assuming a supplier can wait, and avoid delaying a payment if that could create a bigger problem. Borrowing may be worth considering in some situations, but count on it only after confirming availability, terms, and costs. After choosing an action, update the dates and balances to see whether it changes the projected shortfall.
Make the check repeatable
You could update the next four to eight weeks once a month, then review weekly if cash is tight or dates are changing. Treat those intervals as starting points, not standards. Compare expected receipts with what arrived and adjust future estimates when payment patterns differ. The forecast will not make dates certain; it gives you a way to examine a possible pinch point and decide whether to verify, adjust spending, or seek qualified advice.